Fast Cash Flow Fixes: 15 Smart Ways to Cut Spending in a Hurry
Need breathing room fast? These 15 practical money moves help you free up cash today, lower next month’s bills, and avoid costly mistakes that can make a tight budget worse.

If you need to save money quickly, the goal is not perfection. It is to create breathing room without making life unsafe, miserable, or more expensive later. The fastest wins usually come from two places, stopping money leaks today and lowering recurring bills before the next billing cycle.
This guide separates one-time cash relief from recurring savings, shows how long each tactic usually takes, and explains where the biggest impact tends to come from. It also covers tradeoffs, because some so-called savings ideas can backfire through fees, missed payments, or risky shortcuts.
What “saving money quickly” really means
In real life, saving money quickly can mean three different things. First, you might need same-day relief, such as stopping an unnecessary charge before it hits. Second, you might need this week relief, such as cutting grocery spending or selling unused items. Third, you might need next-month relief, such as lowering a phone bill, insurance premium, or subscription stack.
The most useful distinction is this. Some tactics create a one-time bump in cash flow. Others reduce your bills every month. The recurring cuts usually matter more over time.
| Tactic type | What it does | How fast it works | Best use | Limits |
|---|---|---|---|---|
| One-time cash generation | Brings in money by selling items or taking extra work | Same day to 2 weeks | Urgent short-term gap | Not reliable every month |
| Immediate expense cuts | Stops or reduces spending right away | Same day to 1 week | Fast relief | Some cuts are small alone |
| Recurring bill reductions | Lowers monthly fixed costs | Next billing cycle to 30 days | Longer-lasting improvement | May require calls, plan changes, or contract review |
| Budget system changes | Prevents repeat overspending | Same day to 30 days | Keeping gains from disappearing | Takes follow-through |
15 practical ways to save money quickly
| Method | Time to see results | Difficulty | One-time or recurring | Who it helps most |
|---|---|---|---|---|
| Audit subscriptions and recurring charges | Same day to next billing cycle | Low | Recurring | Anyone with multiple apps, streaming, memberships, or trial offers |
| Pause nonessential spending for 72 hours | Same day | Low | Immediate cut | Impulse spenders |
| Build a bare-bones budget | Same day | Medium | System change | Paycheck-to-paycheck households |
| Use pantry meals before shopping | This week | Low | Immediate cut | Households with stocked kitchens |
| Shop with a list and compare unit prices | This week | Low | Recurring | Anyone trying to lower food costs |
| Downgrade phone or internet plans | Next billing cycle | Medium | Recurring | Households with premium plans |
| Ask for bill payment plans or hardship options | Same day to 1 week | Medium | Cash flow relief | People behind or close to behind on bills |
| Review insurance deductibles and discounts | Next billing cycle to renewal | Medium | Recurring | Drivers and homeowners |
| Cut convenience spending | Same day | Low | Recurring | Frequent delivery, vending, or coffee buyers |
| Plan errands to reduce fuel use | This week | Low | Recurring | Car owners |
| Sell unused items with local pickup | Same day to 1 week | Medium | One-time | Anyone with clutter or duplicate gear |
| Set a no-spend day or week | Same day | Low | Behavior reset | People who need a spending reset |
| Use a 24-hour rule for nonessential purchases | Same day | Low | Recurring | Online shoppers |
| Lower credit card interest or prioritize high APR debt | 1 week to 30 days | Medium | Recurring | People carrying balances |
| Automate a small transfer on payday | Next payday | Low | Recurring | Anyone who wants savings to stick |
The fastest ways to free up cash in 24 hours
If you need relief today, start with actions that stop money from leaving your account. Log into your bank and credit card accounts, scan the last 30 to 60 days, and mark every recurring charge. Then cancel, pause, or downgrade anything nonessential. This includes streaming bundles, gaming subscriptions, premium cloud storage, app renewals, and forgotten free trials.
Next, freeze nonessential spending for the next 72 hours. That means no takeout, no convenience store runs, no browsing sales, and no impulse online orders. This is not a forever plan. It is a quick reset that helps you see what spending is automatic rather than necessary.
Then look for same-week grocery savings. Use what you already have before shopping again. Pantry meals, leftovers, and simpler menus can lower this week’s food bill without skipping meals or buying extreme bulk you will not use.
Which expenses should you cut first?
Cut by impact, not by guilt. Tiny daily cuts can help, but the biggest gains usually come from recurring fixed or semi-fixed costs. Start with charges that repeat every month, then move to variable spending that is easy to trim.
| Expense category | Typical savings potential | Speed | What to check first | Common mistake |
|---|---|---|---|---|
| Subscriptions | Low to medium | Same day | Unused services, duplicate streaming, trial renewals | Forgetting annual plans or cancellation deadlines |
| Food | Medium | This week | Takeout, delivery fees, waste, unit prices | Buying sale items you did not plan to use |
| Phone and internet | Medium | Next billing cycle | Plan tier, autopay discount, loyalty offers | Ignoring equipment fees or contract terms |
| Transportation | Medium | This week to next month | Errand batching, insurance review, parking, tolls | Assuming everyone can drive less or sell a vehicle |
| Utilities | Low to medium | This week to next bill | Thermostat habits, hot water use, peak usage | Unsafe cutbacks that risk health or home damage |
| Debt interest | Medium to high | 1 week to 30 days | APR, late fees, hardship options | Using new debt to cover old debt without a plan |
How to cancel subscriptions without getting hit by hidden fees
A subscription audit is one of the fastest money moves because it can stop repeat charges immediately. Search your email for words like renewal, membership, trial, receipt, and thank you for your purchase. Then compare those results with your bank and card statements.
Before canceling, verify three things. First, whether the charge is monthly or annual. Second, whether there is a cancellation deadline before the next renewal. Third, whether canceling removes a bundle discount that affects another service.
Take screenshots of cancellation confirmations and save confirmation emails. If a company makes cancellation difficult, use the provider’s official support channels and document the date, time, and method. The Federal Trade Commission has consumer guidance on subscription traps and cancellation issues.
How to reduce grocery spending this week
Food is one of the easiest categories to trim quickly, but only if you focus on waste and convenience costs instead of extreme restriction. Start by checking what you already have. Build meals around pantry staples, freezer items, and perishables that need to be used first.
When you shop, use a short list and compare unit prices, not just sticker prices. Unit price tells you the cost per ounce, pound, or count, which makes it easier to spot the better value. Bulk buying only helps if you have the cash, storage, and a realistic plan to use the food before it spoils.
Delivery apps and frequent small trips can quietly inflate your total through fees and impulse buys. One planned trip is usually cheaper than several unplanned ones.
A simple tight-budget meal planning approach
Choose a few low-cost meals that share ingredients, such as rice, beans, pasta, eggs, oats, potatoes, frozen vegetables, or rotisserie chicken used across multiple meals. The goal is not to eat perfectly. It is to reduce waste and avoid expensive convenience spending.
Do not use meal skipping as a money strategy. If food is already not stretching far enough, check whether your household may qualify for SNAP, WIC, school meal support, or local food assistance.
How to lower utility costs safely
Utility savings matter, but safety comes first. The best quick wins are moderate thermostat adjustments, shorter hot water use, full laundry and dishwasher loads, and turning off unnecessary lights and electronics. If your utility offers time-of-use pricing, shifting some usage away from peak hours can help.
Avoid unsafe shortcuts. Do not keep your home so cold that pipes freeze or moisture problems develop. Do not reduce heat or cooling to levels that create heat illness risk, especially for older adults, infants, or people with medical conditions. If medication storage or medical equipment is involved, follow clinician or manufacturer guidance.
If your bill is already hard to manage, call the utility and ask about budget billing, payment plans, or hardship programs. LIHEAP and local utility assistance programs may also help eligible households.
How to negotiate phone, internet, insurance, and other bills
Negotiation works best when you are specific. Before you call, know your current plan, your monthly total, any equipment fees, and at least one competitor price. Ask whether there is a lower-cost plan, a loyalty discount, an autopay discount, a hardship option, or a way to remove extras you do not use.
| Bill type | What to ask for | How soon savings may appear | What to watch for |
|---|---|---|---|
| Cell phone | Lower data tier, autopay discount, remove device protection you do not need | Next billing cycle | Reduced hotspot or data limits |
| Internet | Promotional rate, lower speed tier, equipment fee review | Next billing cycle | Contract terms, modem return rules |
| Insurance | Bundling, mileage discount, deductible review, policy comparison | Next cycle to renewal | Do not drop needed coverage to save a little |
| Utilities | Budget billing, payment plan, hardship support | Same day to next bill | Late fees if you miss plan terms |
| Medical bills | Itemized bill review, payment plan, financial assistance | Same day to 30 days | Discuss care or medication changes with a clinician when relevant |
If you carry credit card balances, ask about hardship programs or a lower APR. High-interest debt can erase savings quickly. Be careful with balance transfers or consolidation offers, because fees, promo deadlines, and missed payments can make them more expensive than they first appear.
What to sell first for fast cash
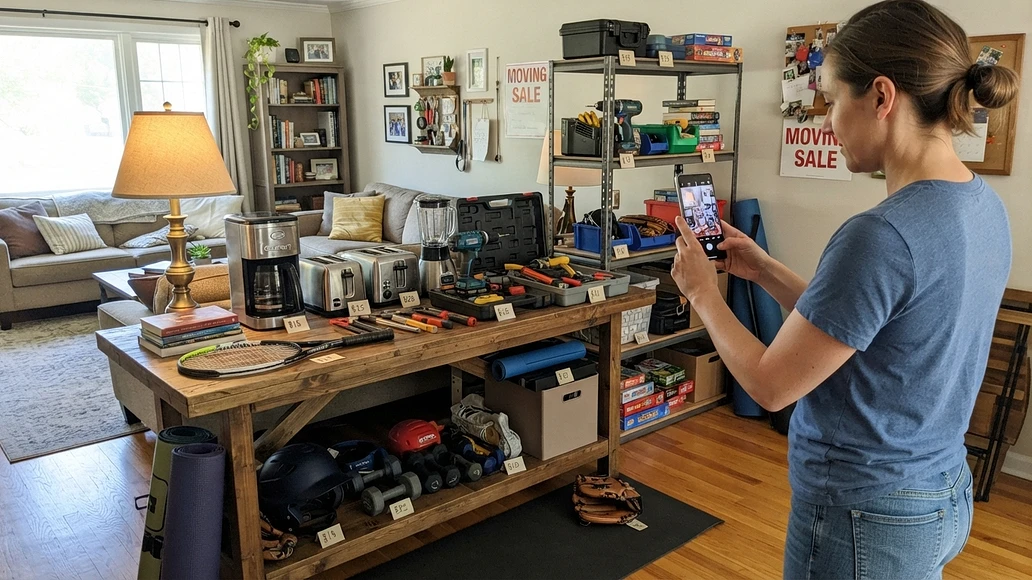
Selling unused items can create quick breathing room, but it is one-time relief, not a monthly fix. Start with things that are easy to price and easy to move locally, such as tools, small appliances, unopened household goods, sports gear, baby items, furniture in decent condition, or duplicate electronics.
Local pickup is often faster than shipping. Clean the item, take clear photos in daylight, write an honest description, and check recent sold prices instead of wishful asking prices. Meet in a safe public place when possible.
Do not sell essentials that you will need to replace soon. A fast sale is not a real savings win if it creates a more expensive problem next month.
How to stop impulse spending before it starts
Impulse spending is often a systems problem, not a character flaw. The easiest fix is friction. Remove saved card numbers from shopping sites, unsubscribe from retail texts and promo emails, and use a 24-hour rule for nonessential purchases. If you still want the item tomorrow and it fits your budget, revisit it then.
Another useful tactic is to keep a wish list instead of a cart. Many purchases lose their urgency after a day or two. This works especially well for online shopping, where convenience makes spending feel smaller than it is.
How to use a no-spend day or week
A no-spend day means buying only true essentials, such as housing, utilities, medication, transportation to work, and groceries already planned. A no-spend week is the same idea for a longer stretch. This can work as a reset, especially if spending has become automatic.
By itself, though, a no-spend challenge mostly eases symptoms. If you go right back to the same habits afterward, the savings disappear. It works best when paired with a subscription audit, a grocery plan, and a bare-bones budget.
How to build a bare-bones budget in one sitting
A bare-bones budget is a temporary spending plan that covers essentials and protects the most important bills first. It is useful when money is tight, income is irregular, or you are trying to stop a shortfall from turning into debt.
List your take-home income, then sort expenses into four groups. Group one is essentials, such as housing, utilities, food, transportation for work, insurance, medication, and minimum debt payments. Group two is important but adjustable, such as phone plans, internet speed, and groceries above your base plan. Group three is optional spending. Group four is savings or extra debt payoff if you have room.
If the math does not work, do not wait for late fees to pile up. Contact providers early and ask about payment plans or hardship options.
| Budget category | Examples | Priority level | Action if money is short |
|---|---|---|---|
| Essential fixed expenses | Rent, mortgage, utilities, insurance | Highest | Pay first, ask about plans if needed |
| Essential variable expenses | Groceries, fuel, medication | Highest | Trim waste, not safety or health |
| Adjustable services | Phone, internet, subscriptions | Medium | Downgrade, pause, or cancel |
| Optional spending | Dining out, entertainment, impulse buys | Lowest | Pause completely for now |
| Savings and extra debt payoff | Emergency fund, extra principal | Depends on situation | Keep a small automatic amount if possible |
Which tactics shorten the problem, and which only ease symptoms?
Some ideas feel productive but do not change much on their own. Cashback apps, coupons, and tiny daily cuts can help, but they rarely solve a serious cash flow problem unless they are paired with bigger moves.
| Usually shortens the problem | Usually eases symptoms | Why it matters |
|---|---|---|
| Canceling recurring subscriptions | Couponing without a meal plan | Recurring cuts keep working every month |
| Lowering fixed bills | One-off no-spend challenges | System changes outlast motivation |
| Negotiating payment terms or rates | Tiny daily cuts alone | Big categories matter more than small leaks |
| Selling unused items | Buying discounted items you did not need | Not every “deal” lowers total spending |
| Automating savings or debt payments | Tracking every penny without changing habits | Simple systems are easier to maintain |
How to save money if you are living paycheck to paycheck
If every paycheck is already spoken for, focus on protecting essentials and preventing expensive mistakes. Late fees, overdrafts, reconnection fees, and high credit card interest can snowball fast. Turn off nonessential autopay items first, but keep essential bills organized so you do not accidentally miss something critical.
If you are choosing between essentials, seek help early. Nonprofit credit counseling, utility assistance, SNAP, WIC, local food programs, and other benefits can relieve pressure without the long-term damage of high-fee borrowing. Payday loans, expensive cash advances, and similar products are not a savings strategy. They often make the next month harder.
Common mistakes that make “saving” more expensive
The biggest mistake is cutting randomly instead of by impact. Another is chasing bargains that increase total spending, such as buying in bulk without a plan, keeping subscriptions because they are on sale, or driving across town for a small discount that burns fuel and time.
Other common mistakes include canceling useful coverage without understanding the risk, ignoring debt interest while focusing only on small purchases, and waiting too long to call providers when bills become hard to manage. If you do side work for extra income, remember that taxes, mileage, supplies, and self-employment costs can reduce what you actually keep. Extra income is helpful, but it is not guaranteed.
When to get help from a nonprofit or professional
Get help sooner rather than later if bills are already delinquent, if you cannot cover essentials like housing, utilities, food, or medication, or if you are using new borrowing to make old payments. A nonprofit credit counselor may help you review options, organize debts, and avoid scams. Government and nonprofit assistance programs may also help with food, utilities, and other basics.
For budgeting basics and debt issues, the Consumer Financial Protection Bureau offers practical consumer guidance. USA.gov can help you locate benefits and assistance programs. If utility bills are the main problem, LIHEAP may be worth checking. If food costs are the pressure point, SNAP information is available through USDA.
References
- Consumer Financial Protection Bureau, Budgeting
- Consumer Financial Protection Bureau, Debt Collection and Bill Problems
- Federal Trade Commission, Cancelling Subscription Traps
- USA.gov, Benefits and Assistance Programs
- USDA, Supplemental Nutrition Assistance Program
- Administration for Children and Families, LIHEAP
- Federal Reserve, Economic Well-Being of U.S. Households